You might not be entirely familiar with the term neobanking. While it’s still not a universally adopted denomination, it describes a sub-industry of Banking that can’t simply be described as “Digital Banking”.
Neobanks are 100% digital, with no physical branches or face-to-face interaction. Instead, they operate solely through digital channels and deliver services via web and mobile apps.
There’s much to be said about these players that challenge traditional banks. So, let’s explore five facts about Neobanks.
1. Neobanks are growing fast
Neobanks have grown impressively in the last few years.
As of August 2019, they had amassed over 30 million customers in total. This figure excludes highly populated markets like China and India. Some estimates predict UK-based challenger banks will triple within 12 months, reaching 35 million users.
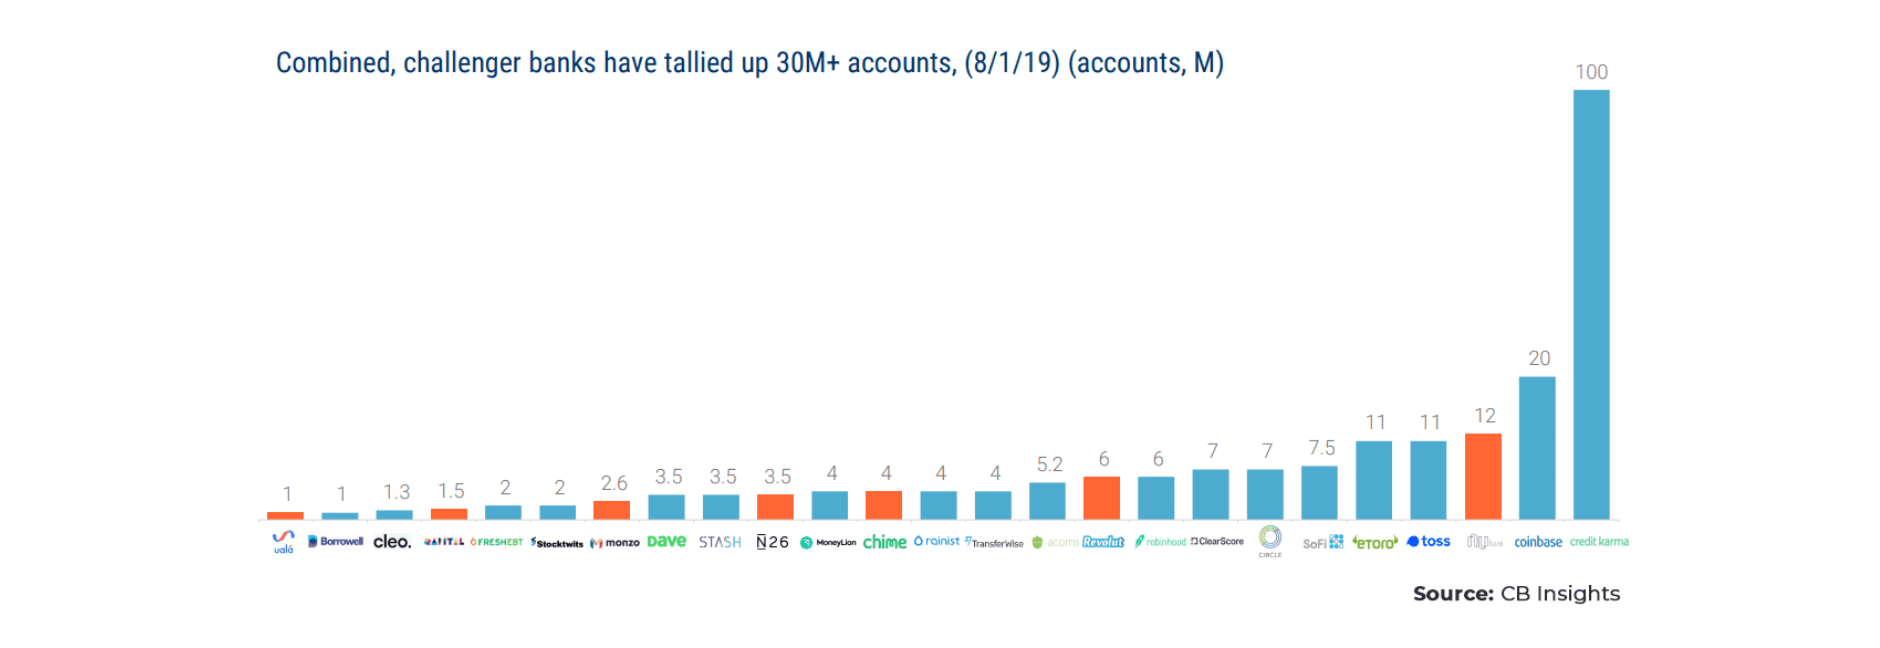
Even among other Fintechs, neobanks are the fastest-growing segment. This growth is largely driven by aggressive investment in Neobanks, with several “unicorn” funding rounds and a combined $2.5 billion invested in 2019.
South America is seeing a rapidly growing number of Neobanking start-ups, with Mexico alone quickly becoming a new “battleground” for challenger banks.
2. Their IT infrastructure is a competitive advantage
Some banking industry analyses suggest traditional banks spend 70% of their IT budget maintaining legacy systems. By contrast, because they don’t have to rely on these legacy systems, neobanks can keep servicing costs up to 70% lower than incumbents.
Neobanks’ IT approach relies on microservices and standardized APIs on the back end, while leveraging open-source front-end frameworks like React Native and Ionic to build modern web and mobile apps.
By betting on these front-end frameworks and third-party JavaScript libraries and scripts, neobanks build modular applications faster and at lower cost. This, in turn, lets them quickly launch new features and update existing ones based on customer feedback.
3 . Neobanking apps are feature-packed and perform much better
As mentioned above, because Neobanks rely on peer-reviewed JavaScript frameworks and libraries, they reduce time to market and iterate quickly.
A 2018 market analysis shows that, on average, Neobanking apps add ten new features per year, compared with six in traditional banks. This includes 27 app updates per year, while incumbents average under 10.
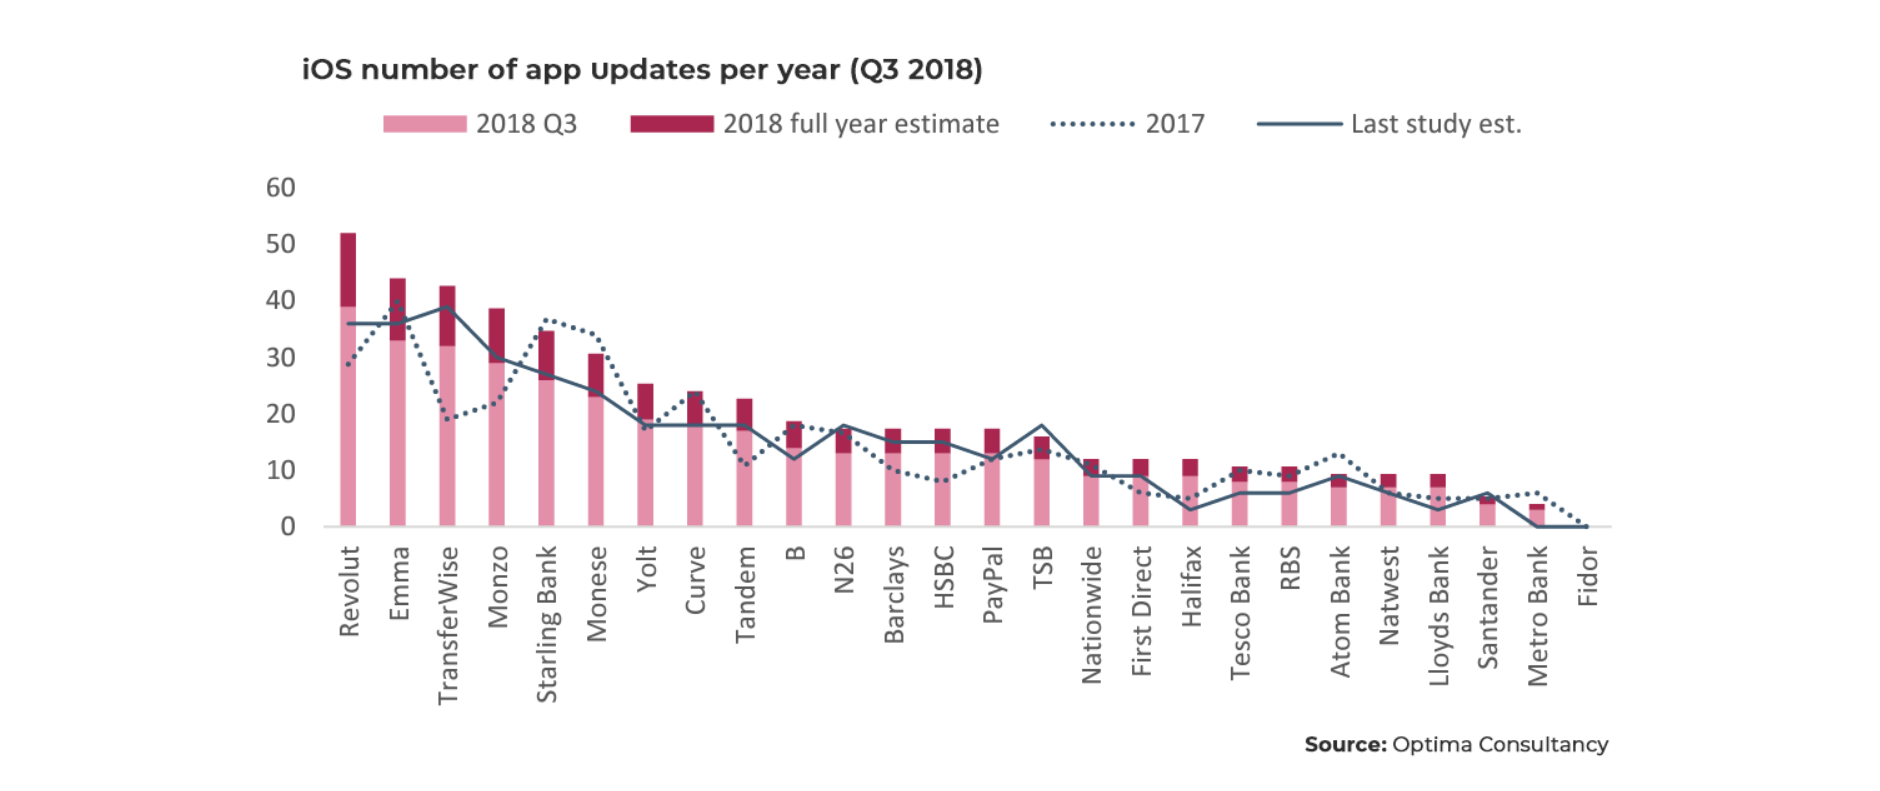 Another aspect of mobile apps is their performance, as users are more demanding than ever about loading times and overall performance. The same 2018 study found that Neobanking apps present a better user experience across the board, performing 42% faster than traditional banking apps.
4. Consumers are happier with Neobanks than with incumbents
Neobanking is fueled by hefty investment rounds. But while one of their KPIs is customer count, they can’t stop at acquisition. Instead, customer retention matters for business sustainability.
To Neobanks, the customer is everything. That’s why so many definitions call them “customer-centric” banks: they base all their actions on customer needs, wants, and continuous feedback.
This customer focus is, unsurprisingly, producing results. Recent U.S. surveys show that 90% of consumers are satisfied with Neobanks, while only 66% are satisfied with the top 50 global banks.
5. Neobanks need to address security to unlock customer trust
To launch product updates quickly and exceed customer expectations, Neobanks often prioritize development speed over security. As a result, two security gaps appear: exposed client-side JavaScript and client-side data breaches.
Exposed JavaScript happens because neobanks place logic on the client side. While this is ill-advised, they often have no choice because storing all JavaScript on the server would hurt performance and the user experience. To mitigate this problem, Neobanks must employ enterprise-grade JavaScript protection to prevent code reverse engineering, debugging, and tampering.
As for client-side data breaches, Neobanks are especially at risk since they integrate external code, mostly npm packages and third-party scripts. Both are gateways for attackers to breach Neobanks without touching their servers.
Instead, by going after Neobanks’ smaller, less secure third-party providers, attackers can launch a web supply chain attack and steal valuable financial and personal data.
Mainstream security approaches, such as Web Application Firewalls (WAFs), fall short of preventing these attacks. To address this threat, Neobanks must gain client-side visibility with a webpage monitoring solution to detect and stop these attacks in real time and keep their users safe.
Conclusion
Neobanks are bringing a new force to the Banking sector. They challenge traditional banks by delivering highly engaging digital banking experiences and are quickly gaining users worldwide.
But guaranteeing a fantastic user experience isn’t enough.
Neobanks still have to earn consumers’ trust in a market where security is everything.
Hence, Neobanks rely on cutting-edge security technology to secure their apps and users’ data. Ultimately, Neobanks will likely redefine the banking paradigm.
If you’re interested in how Jscrambler helps neobanks secure their apps and users, explore our enterprise plans and talk to us!