


Over the past few weeks, online banking growth has become key in every economy.
We’re not only seeing large-scale branch closures, but fears of “infected” cash are also prompting a shift in how consumers pay for goods and services.
Electronic payments look more appealing now as a safer alternative to cash. Against this backdrop, and with the general upsurge in consumer digital banking, what are banks’ key security concerns?
Security in Digital Banking
Consumers are increasingly turning to digital and mobile banking. In some countries, central banks are even encouraging consumers to do so.
For example, in the UAE, the Central Bank has urged bank customers to use digital and online banking services to help ensure residents’ health and safety amid the coronavirus pandemic.
This digital banking trend is even extending to payments. In Italy, one of the first countries to order residents to stay home to prevent the virus from spreading, e-commerce transactions have soared 81% since the end of February, according to McKinsey & Co. estimates.
Amid the fear and worry COVID-19 has generated, industry analysts point to a significant opportunity for incumbents to move digital; they believe the shift in consumer behavior may be permanent.
The Consumer Banking Side
On the consumer banking side, traditional banks will undoubtedly see more adoption of online options, and as people self-quarantine, they will probably avoid bank branches too.
The crisis has provided all the ingredients for a move to digital, and we will see people adopt a wider range of digital financial services. In fact, one recent survey found that 84% of consumers expect banks to maximize digital interaction to keep them safe.
Major neobanks (direct banks that operate exclusively online without traditional physical branch networks) are expanding rapidly.
Neobanks Growth
This is the case with Revolut, which recently launched in the U.S. market; N26, which is seeking to reach more European customers; and Nubank, which is taking Latin America by storm after quickly surpassing 20 million clients.
We are already seeing signs across the globe of incumbents accelerating their digital presence and launching new banking applications. For example, South Africa’s Nedbank is accelerating its digital strategy rollout across Africa as customers move away from face-to-face banking.
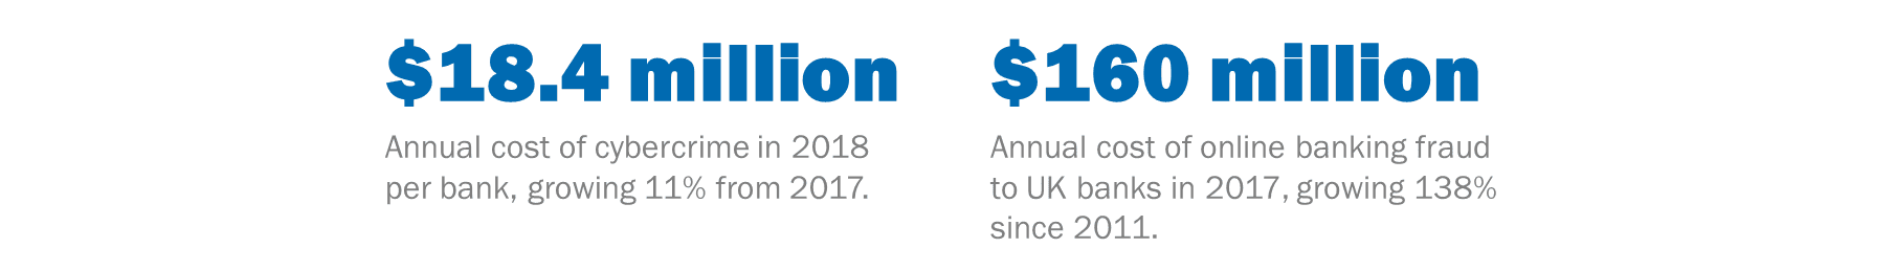 However, financial institutions still face new challenges as they prioritize the move to digital. This is especially true when implementing the infrastructure and procedures needed for online account opening; many financial institutions struggle to open new accounts entirely online, a key differentiator for fintech, challenger, and neo-banks. But a much bigger challenge is keeping customers and their data safe.
Because most digital banking providers rely on fast, agile product development to keep up with consumer demand, they often sacrifice security for a quicker go-to-market.
We’ve seen an increasing trend of banking applications built with JavaScript, a programming language with a large ecosystem and a strong culture of code reuse.
The shift to this new application development strategy requires banks to consider a whole host of new security threats.
Web and Mobile Banking Apps Attack Surface
Web and mobile banking apps have a considerable attack surface, even if we discount code vulnerabilities and security testing tools like SAST and DAST.
Even if banking app teams find and fix every vulnerability in their JavaScript code, it will still be plain, easy-to-understand code.
Just as we can look at this code and understand how the banking application works, so can any attacker. Because these development teams rely heavily on third-party code, they also need to be prepared for web supply chain attacks.
And this is where banks must consider this additional threat and ask themselves, “What would it cost us if someone were to tamper with our code to find ways to exfiltrate our users’ data?”
When so much is on the line, asking more questions and taking a holistic approach to security will help banks keep customers safe amid this unforeseen acceleration in banking digitalization.
To protect your banking platform’s code with Jscrambler, start your free trial today.